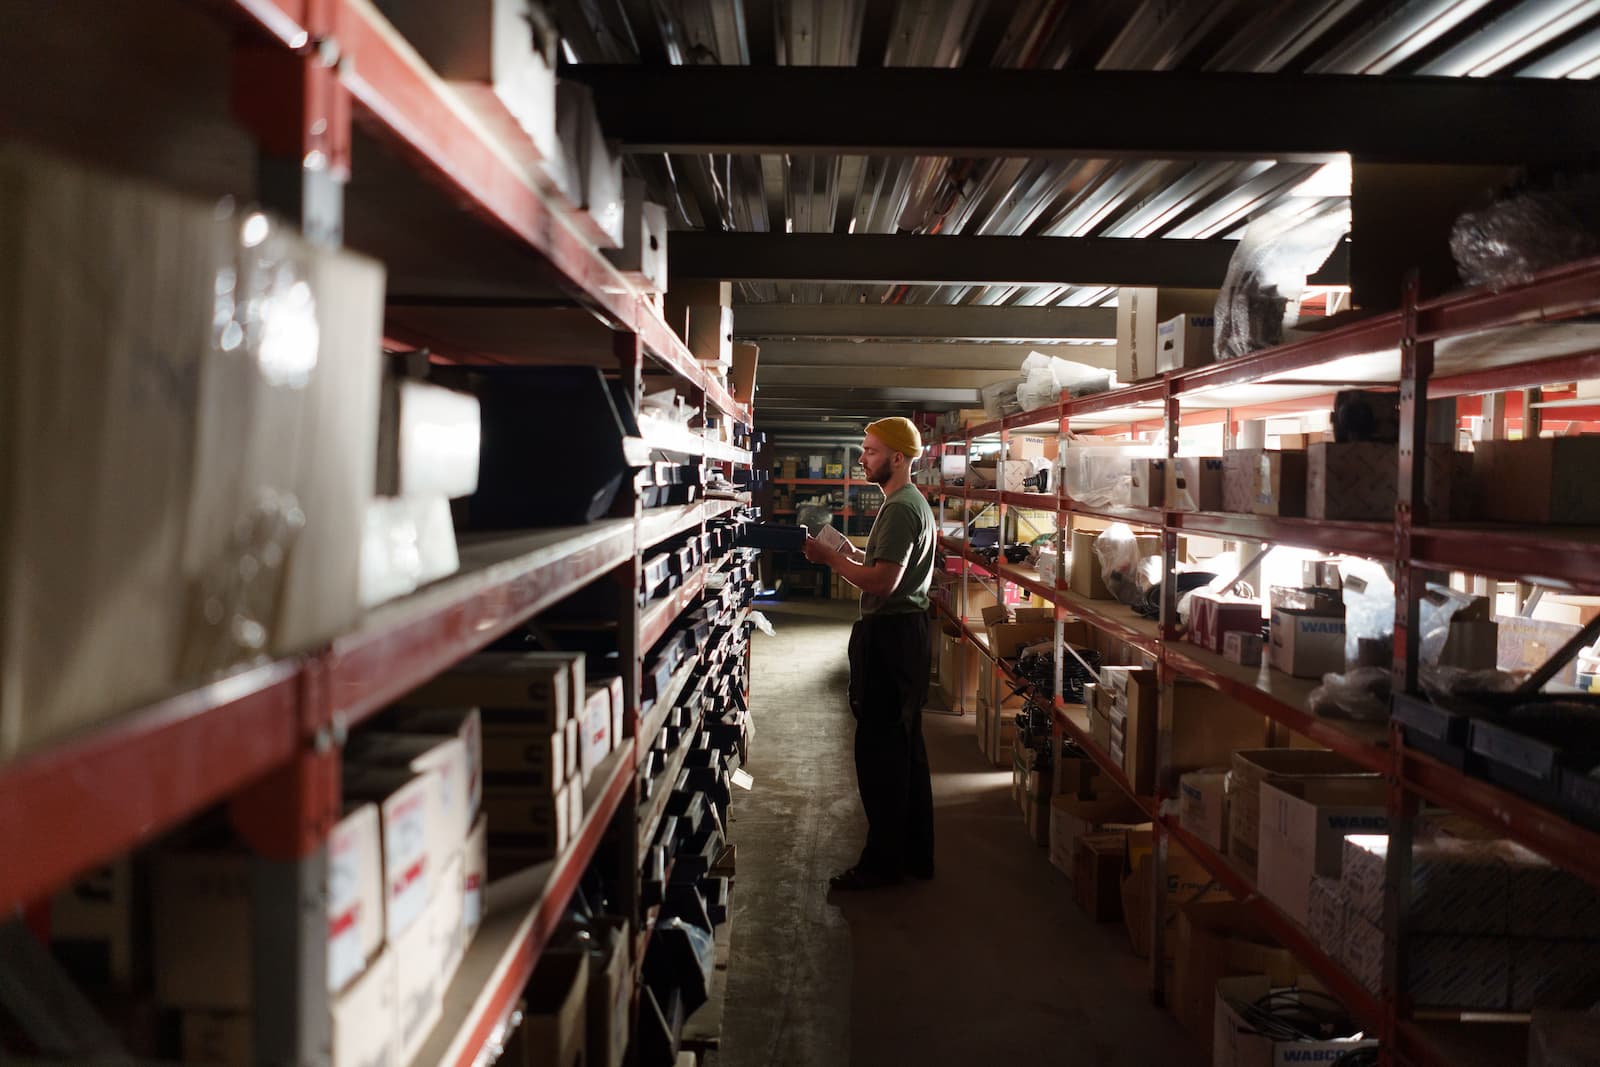
Getting holiday inventory wrong costs retailers real money on both sides of the mistake. A survey by retail think tank Coresight and inventory firm Celect found non-grocery retailers missed out on an aggregate 12% of total sales, roughly $300 billion, due to markdowns, with more than half of those unplanned markdowns blamed directly on inventory misjudgments. One Park Financial has spent over a decade helping business owners fund exactly this kind of seasonal inventory build without guessing. If you are trying to figure out how much to buy before December and how to pay for it, checking your prequalification takes about two minutes, and the breakdown below covers both sides of that decision.
Key Takeaways
Unplanned markdowns, often caused by inventory misjudgments, have cost non-grocery retailers an aggregate 12% of total sales in past research.
Buying too little inventory means losing sales during your strongest month, while buying too much with cash alone can leave a business without a cushion right when it needs one.
Two to three years of historical sales data by product and time period is a far more reliable guide than instinct or last year’s single result.
Financing inventory instead of paying entirely in cash preserves the reserves a business needs to handle whatever December actually brings.
The Expensive Mistake of Buying Inventory by Instinct
Guessing at December inventory needs is a more expensive habit than most business owners realize. Research from Coresight and Celect found that unplanned markdowns, cost retailers an aggregate 12% of total sales, and inventory misjudgments were blamed for more than half of those unplanned markdowns specifically. That is not a rounding error, it is a direct hit to margin caused by buying the wrong amount of the wrong products, not by weak demand or poor pricing.
The mistake runs in both directions. Overbuying ties up cash in stock that eventually gets marked down to move, while underbuying means turning away paying customers during the one month most retailers depend on most. Both outcomes are avoidable with the same fix: basing the purchase decision on data instead of a gut feeling about how this December will go.
How to Use Your Own Sales History to Calculate What You Actually Need
The most reliable starting point is your own historical sales data, ideally two to three years of it where available, broken down by product, by week, and by channel. That history reveals your actual demand pattern rather than a single data point from last year that might have been unusually strong or unusually weak. Tracking vendor lead times alongside that sales history matters just as much, since knowing how long it actually takes a supplier to deliver changes how far in advance you need to place the order, not just how much to order.
Comparing your calculated inventory need against the different types of business loan options available is worth doing once you have a real number, rather than deciding how to pay for inventory before you know how much of it you actually need. A business loan sized to the actual gap in your sales history, not a round number pulled from last year’s invoice, is what keeps the purchase from becoming its own cash flow problem.
Why Paying Entirely in Cash Can Be a Mistake This Month
Paying for a large seasonal inventory order entirely out of cash feels conservative, but it can leave a business dangerously thin right before its highest-stakes month. Calculating how many cash buffer days your business currently has before committing cash to inventory tells you exactly how much of a cushion you would have left if sales come in lower than expected, or if an unrelated expense hits the same month.
This is the core tradeoff: cash spent on inventory is cash that is no longer available to cover payroll, rent, or an unexpected cost while you wait for that inventory to sell through. Financing part or all of the purchase instead keeps that reserve intact, which matters most in exactly the month where things are least predictable.
Matching the Financing to the Purchase
A working capital loan is built specifically for this kind of ordinary, recurring need, covering the inventory purchase while revenue from holiday sales catches up to pay it back, rather than financing a long-term asset the way an equipment loan would. For businesses that are still finalizing exact quantities closer to the ordering deadline, a business line of credit offers more flexibility, letting you draw only what the final order actually costs instead of committing to a fixed loan amount before the number is locked in.
Either structure accomplishes the same core goal: separating the inventory decision from the cash reserve decision, so that getting the quantity right doesn’t come at the cost of leaving the business with no cushion. Financing the purchase, whether through a business loan, a line of credit, or a merchant cash advance, instead of draining cash protects you from entering your busiest month with no cushion left.
What Happens to the Inventory That Doesn’t Sell
Even with good forecasting, some amount of unsold inventory is normal. What separates a manageable amount of leftover stock from the kind of markdown spiral that erodes margin is whether the original purchase was sized against real data in the first place. A purchase based on two to three years of actual sales history will typically produce a smaller, more manageable leftover than one based on a single strong season or pure optimism about this year being bigger than the last.
Planning a modest clearance strategy in advance, rather than reacting to leftover stock in January, also protects margin better than discounting reactively once the pressure to clear shelf space sets in.
Buy the Right Amount, Finance the Rest
The inventory decision and the financing decision are really two separate problems that get solved together. Getting the quantity right protects you from lost sales and markdown losses. Financing the purchase, whether through a business loan, a line of credit, or a merchant cash advance, instead of draining cash protects you from entering your busiest month with no cushion left. Treating both as part of the same December planning exercise, rather than deciding one and improvising the other, is what keeps a strong sales month from becoming a cash-strapped one.
Frequently Asked Questions
How much inventory should I buy for the holiday season?
Base it on two to three years of your own historical sales data by product and time period where available, rather than instinct or a single prior season, since inventory misjudgments are a leading cause of unplanned markdowns.
Should I pay for holiday inventory in cash or finance it?
Financing part or all of the purchase, through a business loan, working capital financing, or a line of credit, preserves your cash reserves for payroll, rent, and unexpected costs during your highest-stakes month.
What’s the difference between a working capital loan and a line of credit for inventory?
A working capital loan works well once you know the exact amount needed, while a line of credit offers more flexibility if you’re still finalizing quantities closer to the ordering deadline.
How costly are inventory misjudgments for retailers?
Research from Coresight and Celect found unplanned markdowns cost non-grocery retailers an aggregate 12% of total sales, with more than half attributed directly to inventory misjudgments.
What should I do with inventory that doesn’t sell after the season?
Plan a modest clearance strategy in advance rather than reacting in January. A purchase sized against real historical data typically leaves a smaller, more manageable surplus than one based on guesswork.
Can a merchant cash advance help cover a last-minute inventory order?
It can, especially if you need funding quickly and want repayment tied to upcoming holiday sales rather than a fixed monthly schedule.
Since 2010, One Park Financial has facilitated over $1.5 billion in funding for small business owners across the United States, connecting them with a network of funding partners offering amounts from $10,000 to $1.5 million. Prequalifying takes about two minutes, requires no paperwork upfront, and does not impact your credit. Businesses that have been operating for at least three months and generate at least $10,000 in monthly revenue may qualify. Find out today if your business qualifies.
Jonathan Jaimes
Senior Content Manager
One Park Financial's editorial team brings together funding specialists, business strategists, and small business advocates to create practical content for the entrepreneurs we serve.