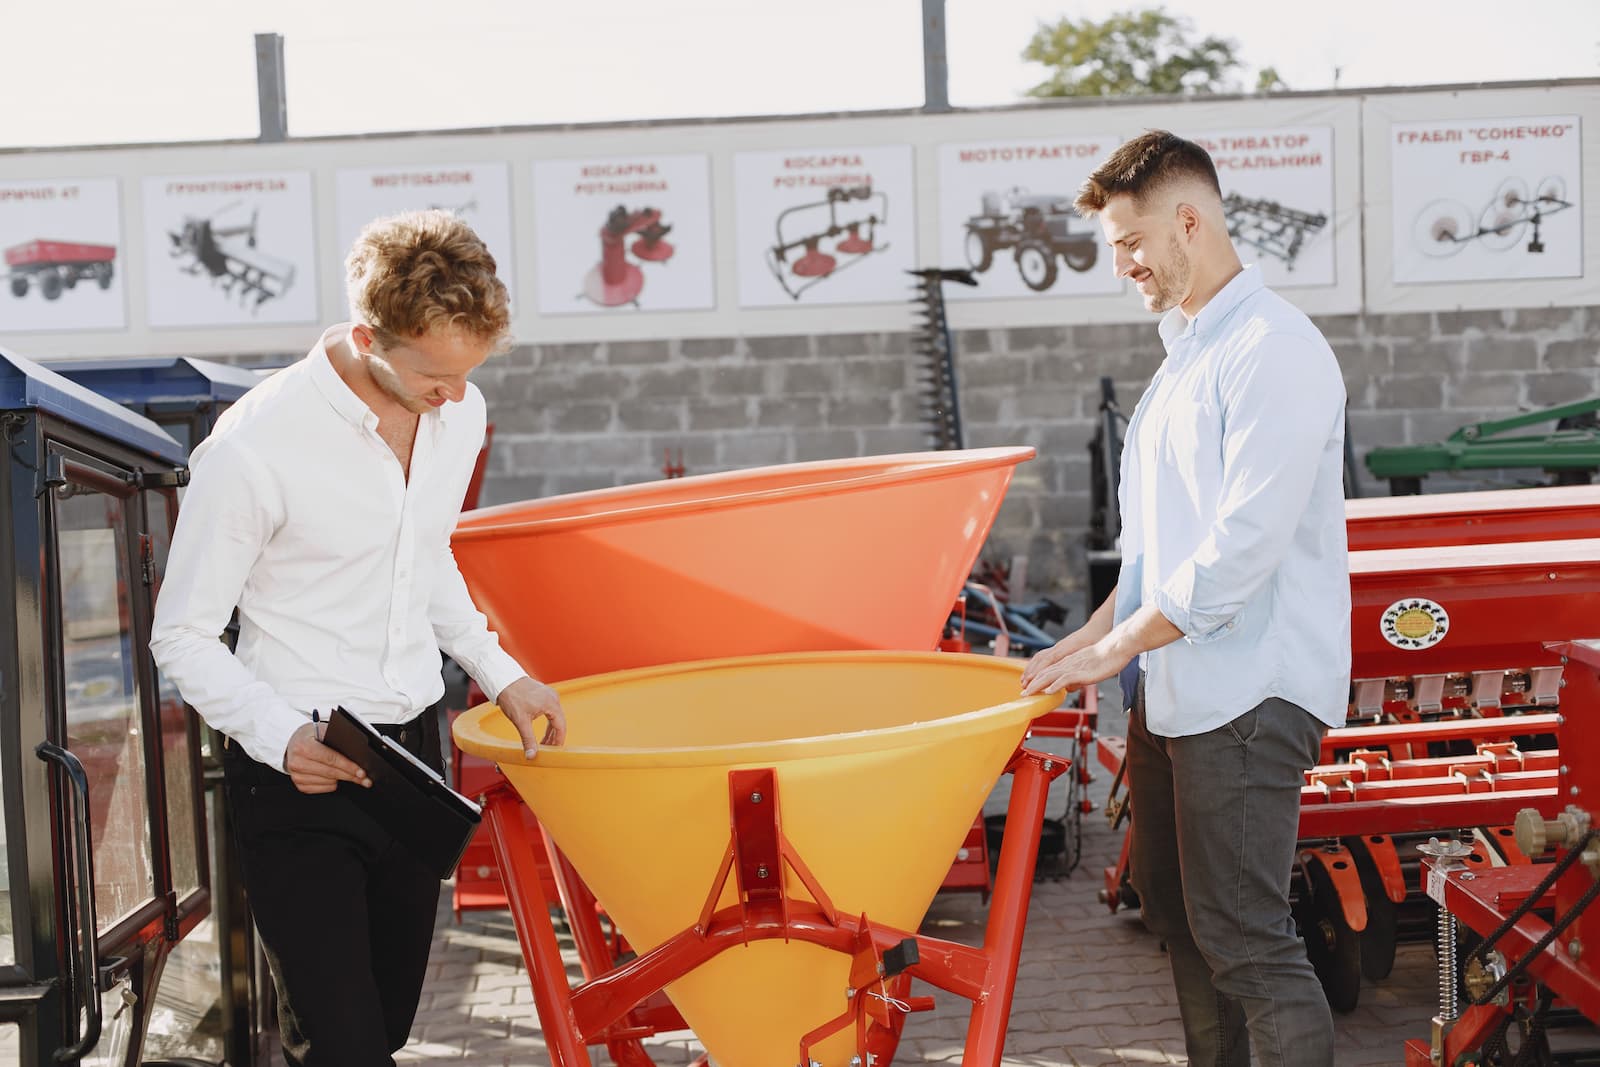
Financing equipment purchases means using outside capital, instead of cash on hand, to acquire machinery, vehicles, or technology, preserving liquidity for operating expenses. Finding out if your business qualifies for funding can be the starting point before deciding how to cover that investment.
Here is a fact that surprises many business owners: according to the Equipment Leasing and Finance Association, the trade association representing the equipment finance industry in the United States, most American businesses, regardless of size, use some form of financing or leasing to acquire equipment rather than paying the full amount in cash. This means financing equipment is not a sign of financial difficulty, it is a standard practice among businesses of every size, from small shops to large corporations.
This article explains the most common options for financing equipment purchases, how to decide between paying cash or financing, and which mistakes to avoid during the process so that this decision strengthens, rather than weakens, your business's financial health.
What It Means to Finance Equipment Purchases and Why It Is a Common Strategy
Financing equipment allows a business to acquire machinery, vehicles, technology, or tools needed to operate without depleting its cash reserves all at once. Instead of undercapitalizing itself with one large payment, the business spreads that cost out while the equipment is already generating value or revenue.
This strategy is particularly relevant for businesses that depend on costly machinery to operate, such as restaurants, repair shops, construction companies, or light freight transport businesses. Using capital strategically to generate more revenue, rather than simply covering expenses, is a principle developed in more depth in this article on how to use capital to generate more revenue for your business.
The Most Common Options for Financing Business Equipment
There are several ways to finance equipment, each with different implications. Traditional equipment leasing allows a business to use machinery without direct ownership, usually with lower monthly payments, but without building equity in the asset. Direct equipment financing, where the business eventually owns the asset, typically requires the equipment itself as collateral for the loan.
There are also unsecured working capital options, which a business can use flexibly to purchase equipment directly without pledging other business assets as collateral. This flexibility is especially valuable for businesses that prefer to protect their personal or business assets, a topic explained in detail in this article on unsecured business financing that protects personal assets.
How to Decide Between Paying Cash or Financing Equipment
The decision between paying cash or financing depends mainly on three factors, how much cash the business currently has available, how long the equipment's useful life will be, and whether that equipment will generate enough revenue to cover financing payments while it is in use.
Paying cash makes sense when the business has solid reserves and the equipment is relatively inexpensive relative to total revenue. Financing makes sense when the equipment is a significant investment that will generate value over several years, and the business prefers to keep its cash available for other operational or growth needs.
What to Consider Before Signing an Equipment Financing Agreement
Before committing to any option, it is important to calculate the total cost of financing, not just the monthly payment, including any additional charges over the life of the agreement. It is also important to confirm whether the financed equipment will serve as collateral for the loan, which directly affects what happens if the business needs to renegotiate terms later.
Comparing different available financing options before deciding is a practice that saves considerable money in the long run, a process described in this article on how to compare business financing options. It is also worth reviewing whether alternatives to traditional bank loans exist, especially when speed in the approval process matters, a topic covered in this article on alternatives to bank loans for small businesses.
Common Mistakes When Financing Equipment Purchases
One of the most frequent mistakes is financing equipment over a longer term than its actual useful life, ending up still paying for it long after it needs to be replaced. Another common mistake is not carefully reading the terms covering what happens if the equipment is damaged or becomes obsolete before payments are complete.
A third, particularly costly mistake is failing to project how monthly financing payments will affect the business's overall cash flow during the early months, when the equipment is not yet generating its full revenue potential. Some forms of financing, like revenue based financing, adjust payments according to the business's actual performance, which can reduce this risk, a model explained in this article on what revenue based financing is.
How Equipment Financing Impacts Your Business's Cash Flow
When structured correctly, financing equipment can actually improve cash flow, since the business avoids one large upfront expense and spreads the cost out while the equipment generates revenue. However, when structured poorly, it can become a burden that drains resources month after month without the expected return.
Before committing to any financing, it is useful to review and understand all associated costs, including charges that are sometimes not immediately obvious, an analysis developed in more depth in this article on the hidden costs of business financing.
Frequently Asked Questions
Is it better to finance equipment or pay for it in cash?
It depends on the business's cash reserves and how much value the equipment will generate over time. Financing tends to be preferable when preserving liquidity for other operational needs is a priority.
Can general working capital be used to buy equipment?
Yes, many working capital solutions are flexible and can be used to purchase equipment, cover payroll, inventory, or other operational needs as the business owner decides.
Does One Park Financial require the equipment as collateral?
According to the FAQ published by One Park Financial, the process is designed without requiring collateral, and general parameters include a minimum of $10,000 in gross monthly revenue sustained for at least three months.
How much financing can a business receive to purchase equipment?
According to official information from One Park Financial, available amounts can go up to $500,000, depending on each business's profile and specific needs.
The Right Equipment, Financed the Right Way, Fuels Growth
Financing equipment purchases should not be an improvised decision. When structured correctly, it allows a business to grow without compromising liquidity, while the equipment itself generates the value needed to cover its own cost over time.
One Park Financial works with business owners who need flexible working capital, including for the purchase of essential equipment, without requiring specific collateral. Their success stories document businesses that used strategic financing to acquire key equipment at the right time. If you are evaluating how to finance your next equipment investment, find out today if your business qualifies for funding and take the next step with confidence.
Jonathan Jaimes
Senior Content Manager
One Park Financial's editorial team brings together funding specialists, business strategists, and small business advocates to create practical content for the entrepreneurs we serve.